¥250,000 take-home pay is slightly above average in Japan and enough to live alone, as long as rent stays around ¥70,000 to ¥83,000.
Is 250,000 Yen a Good Salary in Japan?
On take-home pay of ¥250,000 a month, most people in Japan would call your income "average to slightly above average." How comfortable it feels depends heavily on where you live. In central Tokyo, people often describe it as "fine, but a bit tight." In regional cities, the same pay usually feels comfortable.
The difference is mostly rent. Central Tokyo rents eat into the rest of your budget, while regional cities have lower rents and prices, so the same salary stretches further. Whichever city you choose, knowing your monthly income and spending, and keeping fixed costs under control, is what makes living alone sustainable.
The gross salary behind ¥250,000 take-home pay
Japanese payslips show two figures: your gross monthly salary (the amount in your contract) and your take-home pay (what actually reaches your bank account). To take home ¥250,000, you typically need a gross salary of about ¥320,000 to ¥340,000 a month. That works out to roughly ¥4 million to ¥4.5 million a year.
The deductions are income tax, resident tax, health insurance and employees' pension, which together take about 20 to 30 percent of your gross pay. The exact amount varies with your dependents and the municipality you live in. Because tax and insurance are withheld automatically, plan your budget around your take-home figure, not your contract salary.
How ¥250,000 compares with average take-home pay
According to the National Tax Agency's Statistical Survey of Private Salaries (in Japanese) and similar data, full-time employees in their late 20s to early 30s take home about ¥220,000 to ¥240,000 a month on average. So ¥250,000 is a little above average, although plenty of people in expensive cities still feel it does not go far enough.
By gender, men tend to take home slightly more, and many women earn in the low ¥200,000s. In other words, ¥250,000 sits in the middle: not high, not low. With a sensible budget, it supports a stable life on your own.
How a bonus changes your budget
Many Japanese employers pay bonuses in summer and winter, and whether you get one makes a big difference over the year. If each bonus is worth one to two months' salary, your annual income rises sharply, and saving or covering one-off costs becomes much easier.
Without a bonus, everything has to come out of your monthly pay, so budgeting gets tighter. It is risky to choose rent or take on loans that only work if a bonus arrives. Base your everyday budget on your monthly salary and treat any bonus as extra.
Monthly Living Costs on ¥250,000: A Realistic Breakdown
Living alone means paying rent plus food, utilities, your phone, household goods and more.
On ¥250,000 take-home, you can live comfortably with some planning. Start without a plan, though, and you may find life costs more than you expected. Rent is the biggest expense, followed by food, utilities and your phone. The numbers shift with your city and lifestyle, so knowing your own spending pattern is the first step toward saving.
Below are realistic figures and budgets for different rent levels to help you plan.
How much rent can you afford on ¥250,000?
The common rule of thumb in Japan is to keep rent within one-third of your take-home pay. On ¥250,000, that means about ¥83,000.
In areas where prices and rents are high, though, more people choose places in the ¥60,000 to ¥70,000 range so they are not stretched. Once you sign a lease, rent is a fixed cost you will pay for a long time, so choose carefully.
If your employer offers a housing allowance, your real cost is lower, so check whether you are eligible. Every yen you save on rent can go to savings, hobbies or simply breathing room, which is why rent is the first thing to look at when you review your budget.
Food, utilities and phone costs
Excluding rent, typical monthly costs for one person look like this:
- Food: usually ¥20,000 to ¥40,000. If you mostly cook at home, you can keep it in the ¥20,000s.
- Utilities (water, electricity and gas): around ¥10,000 on average, depending on the season.
- Phone and internet: under ¥5,000 a month if you use a budget SIM plan.
Add household goods and socializing, and your living costs excluding rent come to roughly ¥60,000 to ¥80,000. Keeping your budget balanced comes down to how well you manage these variable costs.
Budget by rent: ¥60,000 to ¥100,000
Here is how life on ¥250,000 take-home looks at different rent levels:
- Rent of ¥60,000
You keep ¥190,000 for everything else, leaving more for savings and hobbies. This is a comfortable setup.
- Rent of ¥80,000
A realistic middle ground where you can cover living costs and still save.
- Rent of ¥100,000
You have ¥150,000 left for utilities, food and everything else, so regular saving and surprise expenses get hard.
Rent is the largest fixed cost in your life, so look past the latest features or a trendy address and choose with the long term in mind.
Search for a room
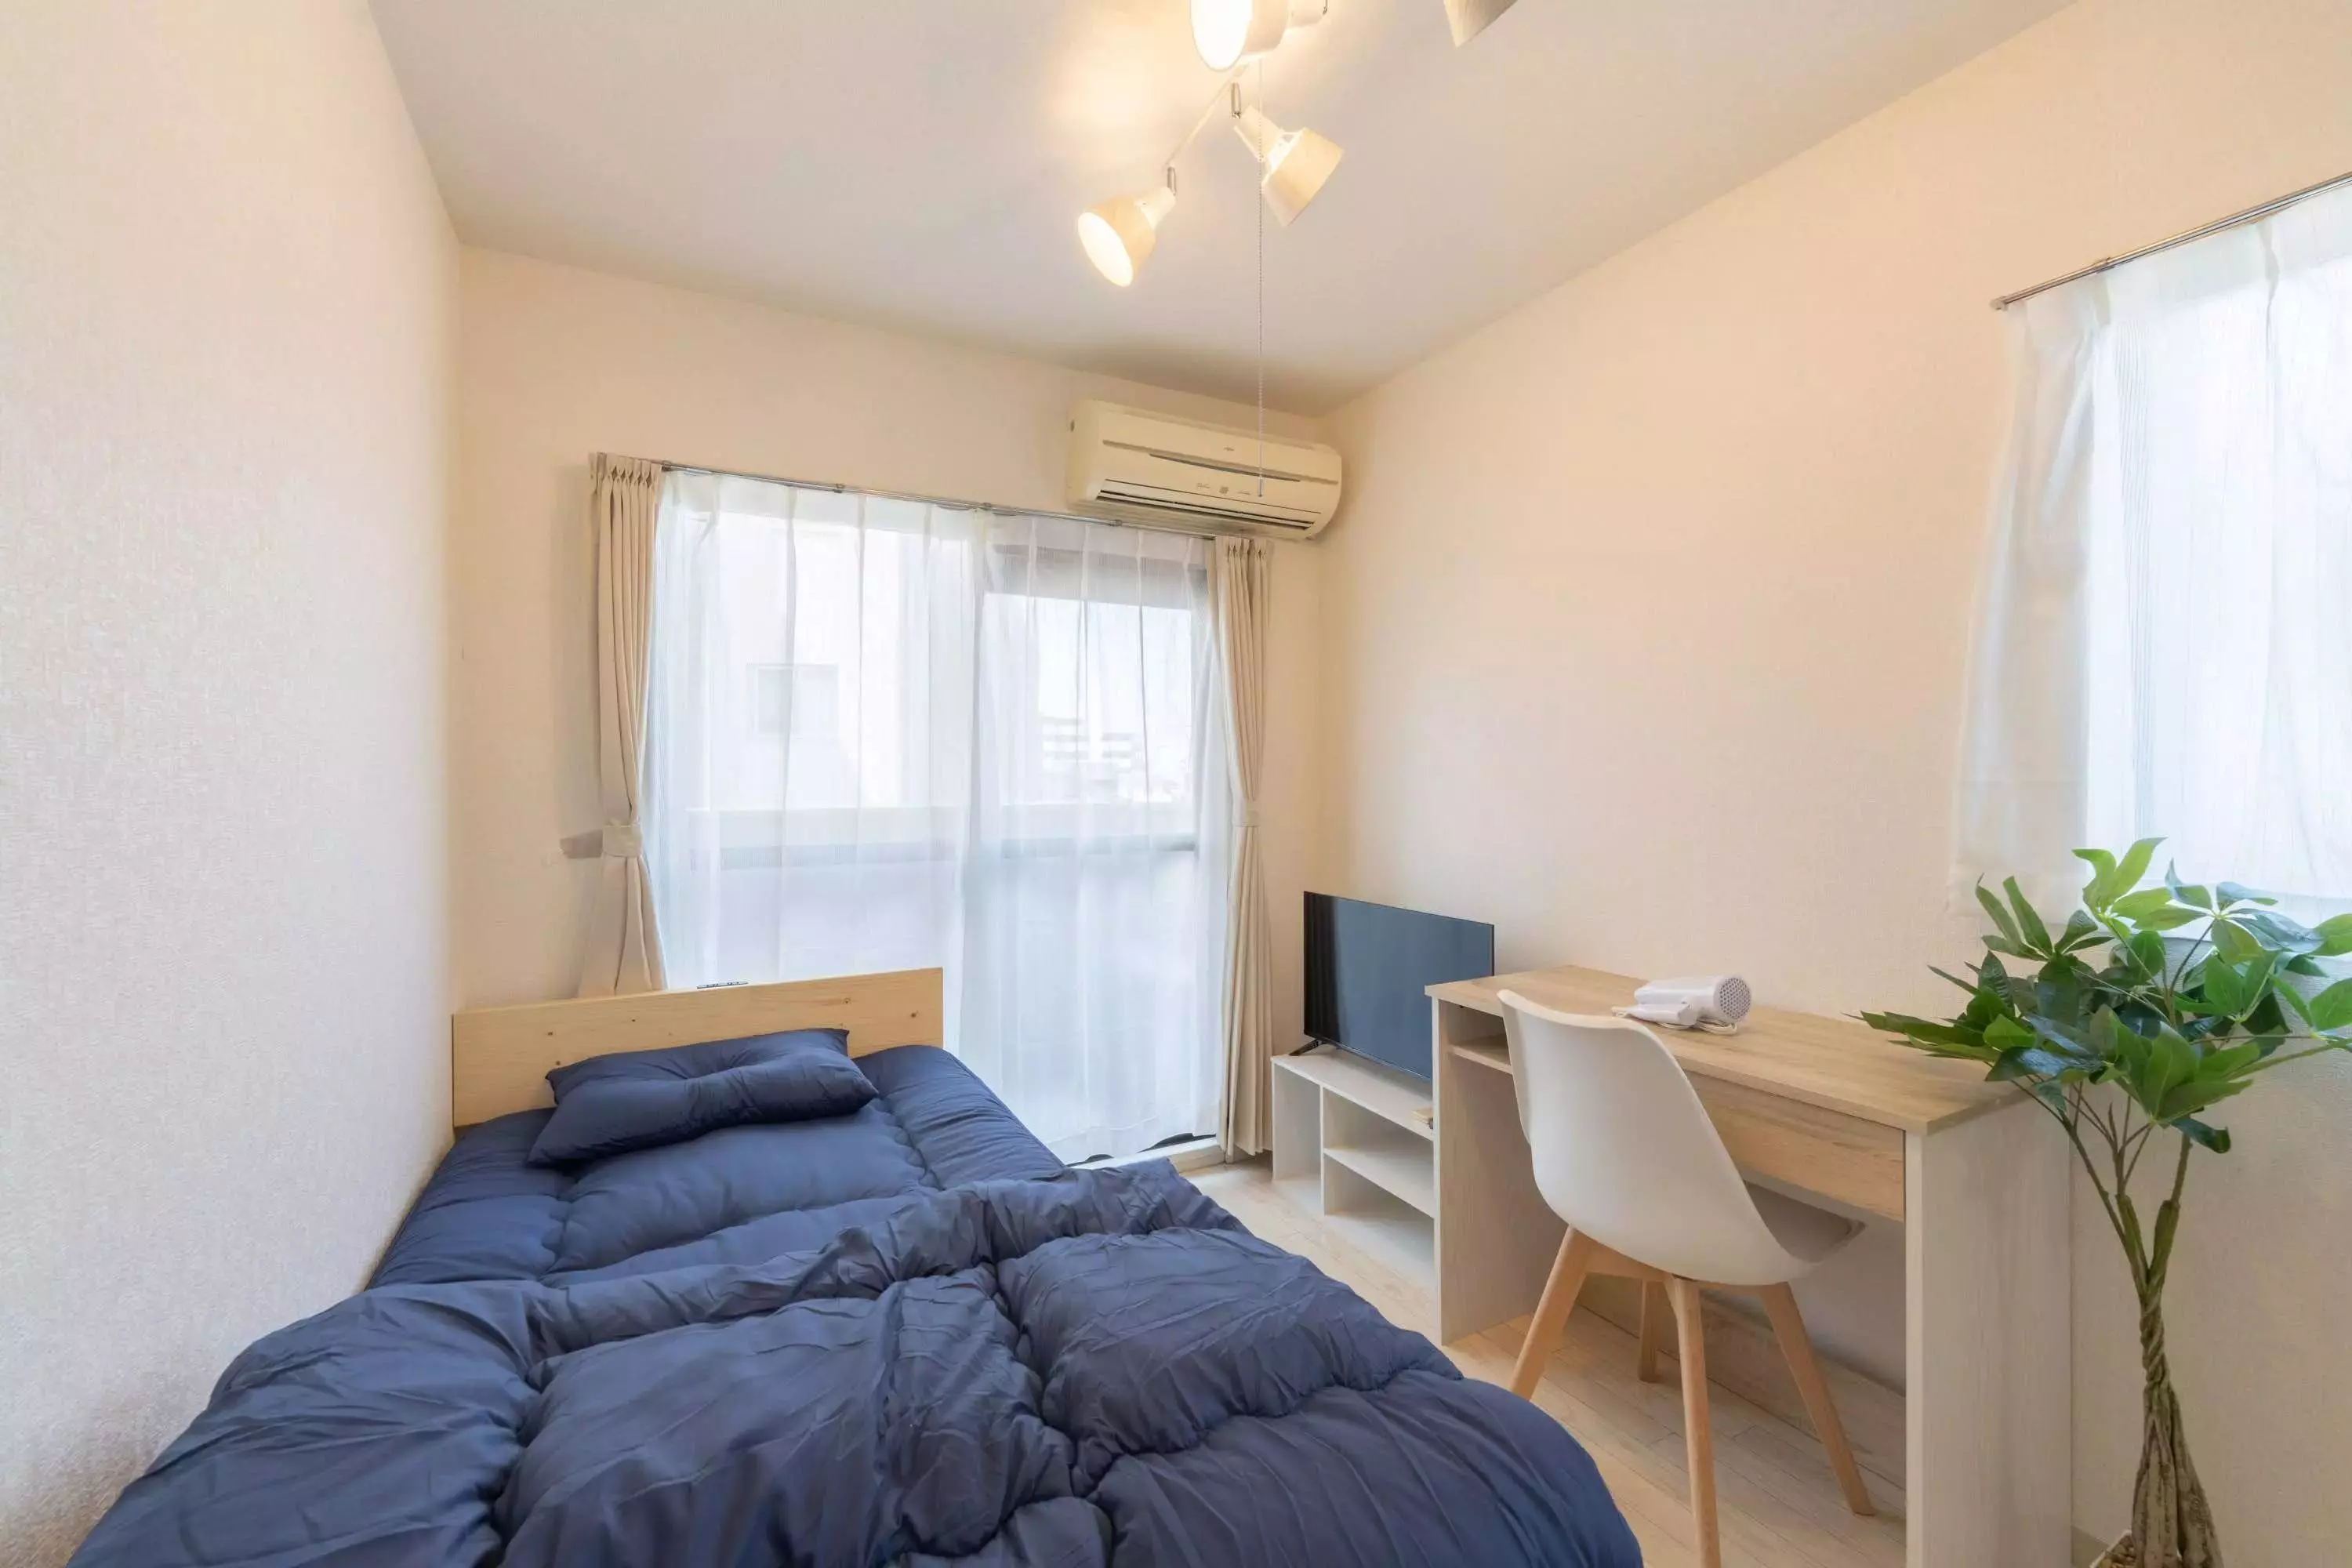
Only furnished properties with appliances are listed!
Why Living Alone on ¥250,000 Can Feel Tight
¥250,000 a month sounds like plenty for one person, yet many people find it tighter than expected.
The main reason is rising rent and living costs. Rents are high in big cities, and food and utility bills have gone up with prices. Socializing, subscriptions and surprise expenses can wipe out what you meant to save. When you live alone you cover every cost yourself, and once your budget slips, the stress builds too.
This section looks at where people actually struggle, and what helps.
What people living alone on ¥250,000 say
Talk to people living on this income and one thing stands out: how comfortable they feel depends on where they live and how they live.
People in regional areas with low rents tend to say "I'm doing fine" or "I save every month." People in central Tokyo and other high-rent areas are more likely to say "Saving? I'm just getting by" or "I've cut back on hobbies and travel."
Bonuses and side income also change the picture. The most common complaint is "Even with a decent income, high fixed costs make it hard." Housing and living costs, more than careless spending, are usually the problem. Decide your rent ceiling and must-haves first, then talk to a real estate agent.
How much do you need to live comfortably?
To live on ¥250,000 without strain, aim to keep monthly spending under ¥200,000.
A comfortable setup looks like this: rent around ¥70,000, living costs (food, utilities, phone, household goods) of about ¥60,000 to ¥80,000, ¥10,000 to ¥20,000 for socializing and hobbies, and ¥20,000 to ¥30,000 going into savings.
In expensive cities, keeping the same standard of living can take ¥270,000 to ¥300,000 in take-home pay. In regional areas with low rents, around ¥200,000 can be enough. Either way, the key is to keep fixed costs low and know exactly what comes in and what goes out.
Where does the money run out?
Most people who struggle on ¥250,000 trip up in two places: rent and variable costs.
If rent is ¥80,000 to ¥100,000, it takes 30 to 40 percent of your take-home pay and leaves little room for everything else. Then the small things add up: your phone bill, subscriptions, eating out and socializing. Before you know it, you are in the red. One-off costs such as medical bills, moving or replacing appliances often force people to dip into savings.
To avoid this, track your spending and run a simple monthly budget. Setting a budget at the start of each month makes running short much less likely.
How to Make ¥250,000 Go Further
Even on ¥250,000 take-home pay, careful budgeting can give you a comfortable life on your own.
Two things matter most:
- Keeping your monthly spending under control
- Finding which costs you can cut, and trimming them
Reviewing fixed costs, cooking at home and saving on utilities add up to a big difference over time. It is not only about spending less. Using reward points and cancelling subscriptions you no longer use are popular ways to save without feeling deprived.
Here are practical ideas for living alone on ¥250,000 with peace of mind.
Budgeting habits that cut spending
Step one is to see where your money goes. A budgeting app shows wasteful spending and the share of fixed costs at a glance, so you know what to fix.
A simple method is to sort spending into fixed costs, variable costs and occasional costs, then set a monthly budget for each. Fixed costs such as rent, your phone plan and subscriptions have the most room for savings, and once you cut them, your monthly spending stays lower.
It also helps to pay yourself first. As soon as your salary arrives, move a set amount into a separate savings account so it never gets spent. If saving never seems to happen, try this first.
Cooking and shopping tips to cut food costs
Cooking at home is the most effective way to save on food. Batch cooking, freezing and planning meals that reuse ingredients can bring your food bill down into the ¥20,000s. Shop once or twice a week and plan meals around what is on sale to avoid waste.
Discount supermarkets, frozen vegetables and canned food also help. Microwave and rice-cooker recipes give you cheap, decent meals with little effort. Aim for ¥200 or less per meal and saving soon becomes a habit. For utility bills, our guide on saving on electricity in a furnished rental has more ideas.
Savings that actually worked
The tips that people living alone say made a real difference are often simple:
- Switching to a budget SIM plan cut a phone bill from ¥8,000 to ¥1,500 a month
- Cancelling unused subscriptions saved more than ¥3,000 a month in fixed costs
- Running the air conditioner on auto with a circulator fan to lower electricity bills
- Buying in bulk from an online supermarket to avoid impulse purchases
The lasting way to save is to change how your life is set up, not to force yourself to go without.
Search for a room
Only furnished properties with appliances are listed!
Planning Ahead: Savings, Extra Income and Where You Live
Getting by each month is only half of it. On ¥250,000, it is worth preparing for the future too. If day-to-day costs leave nothing for savings, sudden expenses and life events such as changing jobs, moving or getting married become hard to handle.
Three things help: building savings, adding income, and rethinking where you live. Working on both sides, earning more and spending less, can make life on ¥250,000 far more secure.
Below are realistic savings targets, ways to raise your income, and housing choices that lower your living costs.
How much can you save each month?
On ¥250,000 take-home, a good savings target is ¥30,000 to ¥50,000 a month.
That is 15 to 20 percent of your income, a level you can keep up. Keep rent at ¥70,000 to ¥80,000, trim food, utilities and phone costs, and hold total spending under ¥200,000, and you can put the remaining ¥50,000 into savings. Clear goals such as "¥300,000 in six months" or "¥500,000 in a year" keep you motivated.
Paying yourself first also stops money from slipping away unnoticed, which makes steady saving much easier.
Raising your income: side work, a new job or a promotion
For long-term security, earning more matters as much as spending less.
Side work has become common in Japan, and there are more ways to earn in your spare time from home, such as writing, design, video editing and data entry. If you are not a Japanese national, check with your employer and the Immigration Services Agency of Japan whether side work fits your status of residence before you start. If you are aiming for a raise or promotion in your current job, qualifications and new skills help. For a bigger jump in pay, consider changing jobs.
Your 20s and 30s are a good time to switch careers and raise your market value. Increasing the money you have to spend is the other half of feeling secure about the future.
Consider a share house
Housing is your biggest chance to cut fixed costs.
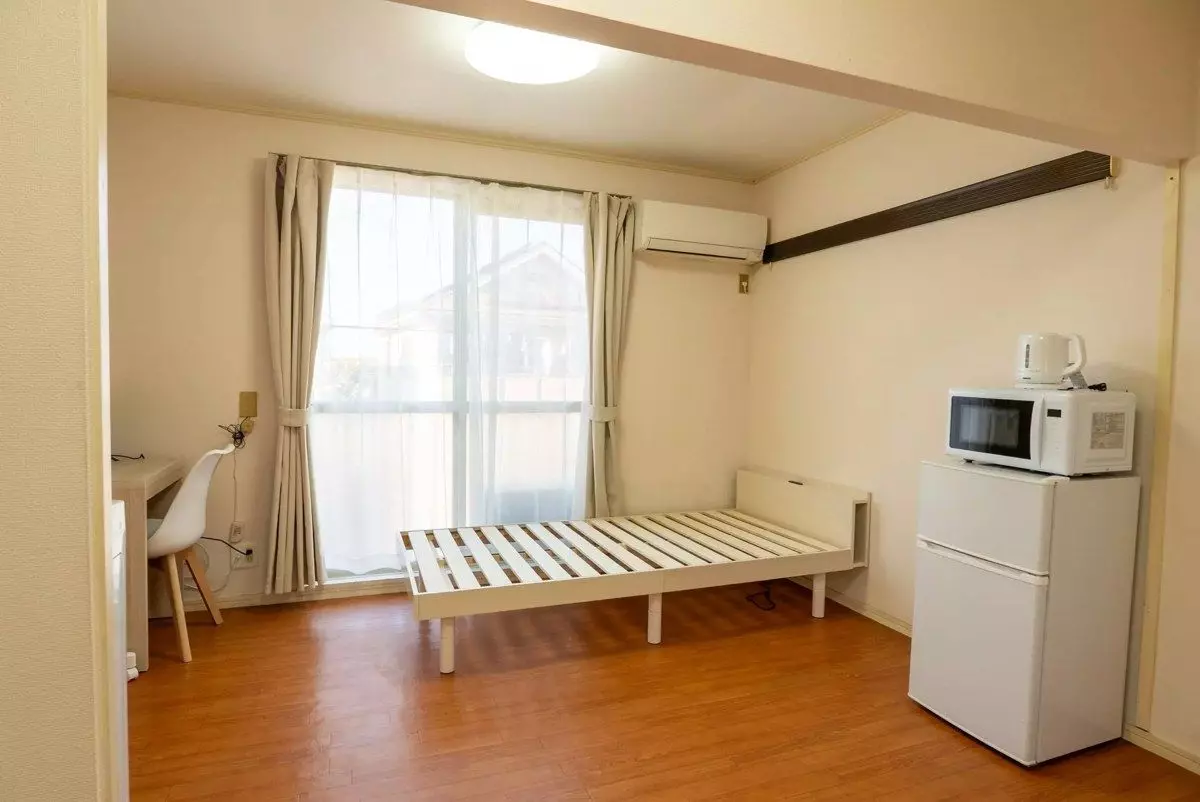
A share house bundles rent, utilities and internet into one lower monthly cost, which gives you real breathing room on ¥250,000. Rooms come furnished with appliances, so you also spend less setting up a new home, and you can put the money you save toward savings, hobbies or new skills. For a closer look at the numbers, see whether share houses are really cheaper and share house vs. living alone.
Compared with renting a standard apartment on your own, a share house changes your budget in a few ways:
- Furniture and appliances: you buy them yourself in a standard rental; they are already in the room in a share house.
- Utilities and internet: separate bills in a standard rental; bundled into the monthly cost in a share house.
- Upfront costs: a standard rental often asks for a deposit and key money; many share houses do not.
Living with others also brings new perspectives and connections. Some people worry about privacy or house rules, so think about whether shared living suits your personality and lifestyle.
Share houses with XROSS HOUSE
If you want to keep rent down and still live comfortably, XROSS HOUSE is one option to look at.
We run share houses mainly in Tokyo and Osaka, with low upfront costs and monthly rents below typical market rates. Rooms come with furniture, appliances and Wi-Fi, and many properties need no deposit, so ¥250,000 take-home leaves you plenty of room. You do not need a personal guarantor. Instead, individual tenants usually join a rent guarantee company, which charges an initial guarantee fee and a monthly guarantee fee on top of our fees. If you pay everything from move-in to move-out costs in full at the start, you do not need to join the guarantee company at all, so there are no guarantee fees. For a full breakdown of what you pay and when, see our fees page.
More than 50,000 people have lived with XROSS HOUSE so far. Some properties have shared lounges where residents get to know each other, and there are plenty of private rooms if privacy matters to you. If you would rather have your own kitchen and bathroom, XROSS HOUSE also offers furnished apartments.
To hear from people who have lived with us, read our XROSS HOUSE reviews.
We have many kinds of rooms. If a share house sounds right for you, try searching for a room.
Frequently asked questions
Is 250,000 yen a good salary in Japan?
As take-home pay, yes. It is a little above the average of about ¥220,000 to ¥240,000 for full-time employees in their late 20s to early 30s. It is enough to live alone, but in central Tokyo it can feel tight if rent is high.
If 250,000 yen is my gross salary, how much will I take home?
Income tax, resident tax, health insurance and employees' pension usually take about 20 to 30 percent of gross pay, so you would keep roughly ¥175,000 to ¥200,000. To take home ¥250,000, you need a gross salary of about ¥320,000 to ¥340,000 a month.
How much rent can I afford on 250,000 yen take-home pay?
The usual rule is one-third of take-home pay, or about ¥83,000. To live without strain, many people aim for around ¥70,000, or ¥60,000 to ¥70,000 in expensive areas.
How much can I save on 250,000 yen a month?
A realistic target is ¥30,000 to ¥50,000 a month. Keep rent at ¥70,000 to ¥80,000 and total spending under ¥200,000, and you can save the rest.
Is 250,000 yen enough to live alone in Tokyo?
Yes, if you keep rent under control. People in central Tokyo often find it tight, and keeping the same standard of living in expensive cities can take ¥270,000 to ¥300,000 in take-home pay. A cheaper room or a share house leaves much more room in your budget.
How much is 250,000 yen in US dollars?
It depends on the exchange rate on the day, so check a live currency converter. For living in Japan, what matters more is what ¥250,000 covers locally: rent of around ¥70,000 to ¥83,000, ¥60,000 to ¥80,000 in other living costs, and some savings.
Do I need a guarantor to rent a XROSS HOUSE share house on this salary?
No personal guarantor is needed. Individual tenants usually join a rent guarantee company instead, which charges an initial and a monthly guarantee fee. If you pay all costs from move-in to move-out up front, you do not need to join the guarantee company. Our FAQ page has more details.
Search for a room
Only furnished properties with appliances are listed!
Summary
Living alone on ¥250,000 take-home pay will not be luxurious, but with a balanced budget it can be comfortable and sustainable.
Rent is the biggest cost, so keeping it in the ¥60,000 to ¥80,000 range gives your budget room to breathe. Small changes such as trimming food and utility bills, cooking at home and switching to a budget SIM add up. To prepare for the future, make saving a habit and look at ways to raise your income. Choosing the right place to live can also lower your living costs.
Use these figures to find the budget and lifestyle that work for you, and enjoy living on your own in Japan.